ECON FUNG RED *.*Economic Implications Concerning The Closing of the Strait of Hormuz (March 2026)

Status
Not open for further replies.
CNBC is currently MOCKING the CRAP out of Democrats and Elizabeth Warren after the latest inflation and strong GDP report.

"The left, the people who don't like the president, don't want things to work. Senator Elizabeth Warren will come on and say, 'Inflation is OUT OF CONTROL, and the economy is getting k*lled by these tariffs!"

"REALLY, we haven't seen inflation go back up...NONE of these horrible things have happened, but they still talk like it's happening, it's amazing!"

RICK SANTELLI: "The Democrats [really] don't want to see the current administration have some success, but there's NO doubt that this is some success."

They have become a laughing stock.

RT 1min
View: https://fxtwitter.com/i/status/2089463849795649576
 
Yuck. Problems abound.

Stock up.

===
.
I've been stocking up since I heard that the Navy set sail to the middle east.

Most years I stock up in late summer/early fall. This year is different. Shortly, I'll do an inventory of my winter clothing, to look for any gaps in my supplies. Size 13+ wool blend/boot-type socks are often difficult to find around here. The other day I went past one store that was one of the better retailers. I haven't been there in about a year, the store is now closed, and the building was being demolished! I likely should adjust my purchases for multi-year use, rather than just the upcoming year.
 

Qatar And Kuwait Restore 70% Of Pre-War Oil Exports Through Hormuz​

Qatar and Kuwait have managed to boost their crude oil exports from the Strait of Hormuz to 70% of pre-war levels as they followed the United Arab Emirates in shuttling oil through the chokepoint and using ship-to-ship transfers in the Gulf of Oman, anonymous traders told Bloomberg on Thursday.

1787858678646.png

Before the Middle East conflict, Qatar and Kuwait collectively exported about 2 million barrels per day (bpd) of crude oil via the Strait of Hormuz.

They don't have alternative routes as Saudi Arabia and the UAE do, and struggled to ship oil out of the Persian Gulf in the first couple of months of the conflict.

But around June, Kuwait and Qatar began shuttling crude out of Hormuz and offered it for transfers outside the chokepoint in the Gulf of Oman.

The increasing Kuwaiti and Qatari oil volumes add to the barrels that Saudi Arabia and the UAE have been sneaking through the Strait of Hormuz and on routes bypassing it since the start of the war.

The UAE has managed to boost its oil exports to pre-crisis levels as early as June, as it has kept pushing crude through the Strait of Hormuz and beyond. It has been shuttling crude through the chokepoint to load it on larger vessels outside the Strait, maximizing the use of its onshore pipeline to ship crude from the west to the east of the country, bypassing Hormuz, and shipping tankers through the Strait in dark mode.

Saudi Arabia, for its part, has also started offering STS transfers of Gulf crude outside Hormuz, and has been using the Red Sea and Egypt's Mediterranean ports to bypass the Persian Gulf's chokepoint.

Thanks to the shuttle services and dark activity, total oil flows through the Strait of Hormuz have now risen to about 7-8 million bpd, up from about 4 million bpd in the middle of July, according to Bloomberg's trading sources.

The under-the-radar operations and the Gulf states' creative solutions to the threats in the Strait of Hormuz and the Red Sea have helped keep oil flowing, even if at much reduced rates compared to February levels.

The higher oil volumes exiting the Persian Gulf have kept benchmark crude oil futures in check despite the tightening global fuel markets.


Global Diesel Breakdown​


26 August 2026 by Larry C. Johnson 105 Comments

XTelegramVKFacebookEmailCopy LinkShare
Author: Karl W. Miller August 26, 2026

(The following article is from Karl W. Miller… His bio is at the end of the piece.)

Physical supply has caught up with the market. Our call: over the next 30 days,
diesel scarcity will transmit directly into freight costs, food prices, agricultural
production, industrial output and inflation. Over the next 12 months, the same
energy shock will move through fertilizer and into global food supply.

Executive Summary​

The world no longer has a meaningful middle-distillate safety cushion. There
are still volumes of finished middle distillates in tanks, pipelines and terminals, but
increasingly they are working inventory required to operate the system, not surplus
diesel and jet fuel capable of absorbing another major outage, export restriction or
shipping disruption. The physical shortage has caught up with the market. Over the
next 30 days, that scarcity will transmit directly into regional availability, freight costs,
food prices, agricultural production, industrial output and inflation. The second wave
is already forming: natural gas and fertilizer scarcity will carry the energy shock into
the 2026/27 growing cycle and food supply.

No cushion does not mean zero inventory. It means there is no longer enough readily available surplus supply to absorb another material shock without forcing an immediate response somewhere else.​

image-32-1024x584.png
Physical-supply stress panel. Data: U.S. EIA; Insights Global / ENGINE; Enterprise Singapore / ENGINE; Singapore Ministry of Trade and Industry.


image-33-1024x256.png

U.S. diesel has moved from a normal-cost environment into scarcity pricing. The national average rose from $3.477 per gallon at the start of the year to $5.652 on Aug. 24. Every PADD is materially higher; the Gulf Coast and Rocky Mountain regions are up more than 70%. That price move is not the shortage itself, it is the market’s attempt to ration limited physical supply.​


image-34-1024x532.png
image-35-1024x566.png
image-36-1024x566.png

The Next 30 Days: How a Diesel Shortage Becomes an Economic Crisis​

image-37-1024x156.png
image-38-1024x774.png


A global balance is meaningless if the required barrel of finished diesel, a refined middle distillate, cannot arrive where demand is physically occurring. Refined middle distillates are regional markets, constrained by refinery configuration, product specification, pipelines, terminals, vessels, port capacity and travel time. Diesel, gasoil and jet fuel compete for the same middle-distillate refinery yield, but a barrel of finished diesel in one market is not instantly interchangeable with jet fuel, and neither product is instantly movable to another region.

When inventories are healthy, local stocks buy the days or weeks required to reroute cargoes from one PADD, one European hub or one Asian market to another. Without surplus inventory, that time bridge disappears. A barrel of finished diesel may exist somewhere else, but it cannot necessarily reach the deficit market before the local terminal, pipeline system or distribution network runs short.


A barrel of finished diesel somewhere else is not a barrel of finished diesel here. With no cushion, distance and delivery time become physical shortage.


Our call is that the global market will split. Better supplied regions will get by only by paying extreme premiums and pulling cargoes away from weaker markets. Other regions will move through allocation, delayed deliveries and terminal level stockouts into actual physical shortages. Either outcome is inflationary, because the scarcity premium is passed into freight, aviation, agriculture, manufacturing and delivered goods.

The diesel crisis is now intersecting with natural gas and fertilizer. Food and energy are two of the most immediate and visible inflation channels in the real economy. Higher diesel raises the cost of planting, harvesting, processing and moving food. At the same time, nitrogen fertilizer, especially ammonia and urea, is heavily dependent on natural gas.

image-39-1024x351.png

Evidence: FAO Food Outlook, June 2026; FAO fertilizer scarcity warning, May 2026; World Bank Commodity Markets Outlook and Food Security Update, 2026.

Our 12 month call is that the world is moving into a synchronized food and energy scarcity cycle. The first transmission is diesel into freight, farming and industrial costs. The second is natural gas into ammonia and nitrogen fertilizer. The third is higher fertilizer prices, reduced application, higher farm costs and tighter food supply through the 2026/27 production cycle. Import dependent regions and economies with limited fiscal capacity will be hit first and hardest.


Diesel is the immediate crisis. Fertilizer is the lagged crisis. Food is where the two converge.


When surplus inventory exists, the system can bridge a refinery outage, a delayed tanker or a temporary export restriction. When spare refining capacity exists, output can rise. When alternative exporters have product to sell, cargoes can be redirected. The present market is losing all three shock absorbers at once, inventory, spare conversion capacity and the time required to move replacement barrels of finished diesel and jet fuel.

The remaining diesel demand is also increasingly essential. Trucks must move food. Farms must operate. Ports, mines, construction equipment, emergency services and backup generators continue bidding for fuel. As discretionary consumption is removed, each additional barrel of diesel demand destruction requires more economic pain.


When there is no meaningful cushion, the price no longer simply tells consumers to conserve. It begins deciding which economic activity still gets fuel.


image-40.png


Our call: the next global economic shock begins with a shortage of finished diesel and other middle distillates, then moves through fertilizer into food.

The world is operating with working stocks but without a meaningful middle-distillate safety margin. Over the next 30 days, diesel scarcity will transmit directly from the shortage of finished middle distillate supply into freight, food, agriculture, industrial output and inflation. Over the next 12 months, fertilizer and natural gas stress will extend that shock into the 2026/27 growing cycle, food supply and food prices.


image-41.png


===
.
 
PADD in the oil and gas industry stands for Petroleum Administration for Defense District. It divides the United States into five geographic regions used to track the movement, supply, and demand of crude oil and refined petroleum products. [1, 2, 3]

History of PADD
    • World War II origins: The U.S. government created these districts in 1942 to ration and allocate gasoline and fuel supplies for the war effort. [1, 2]
    • Modern use: While rationing ended long ago, the U.S. Energy Information Administration (EIA) and industry analysts still use PADD regions today to collect data and study regional market trends. [1, 2]

The Five PADD Regions
The U.S. is split into the following five districts: [1]
    • PADD 1 (East Coast): High fuel consumption with very little local refining capacity, making it heavily reliant on imports and shipments from other regions. [1, 2]
    • PADD 2 (Midwest): A major refining and agricultural fuel hub connected closely to Canadian crude supplies. [1, 2]
    • PADD 3 (Gulf Coast): The heart of U.S. crude production and refining, accounting for a massive share of the nation's oil processing and exports. [1, 2]
    • PADD 4 (Rocky Mountain Region): Includes Montana and neighboring states, characterized by local crude production matching regional interior demand. [1, 2]
    • PADD 5 (West Coast): Includes Alaska, Hawaii, and the Pacific states, operating somewhat as an isolated fuel market. [1, 2]

=====
Provided for definition of PADD in above post.

===
.
 
Well, we're seeing the Economic Implications for closing the Strait of Hormuz...... for IRAN!!

I wonder if they think it was worth it???

Iranian crude oil exports plummet in the face of US blockade of Strait of Hormuz​


On July 14, Trump reimposed the blockade in retaliation for Iran attacking oil tankers transiting the strait. Iran's crude exports are down 70% in August from 893,000 bpd last month.

Iranian crude oil exports have plummeted as the U.S. reimposes its naval blockade of the Strait of Hormuz as part of President Donald Trump's plan to put economic pressure on the regime into ending its own blockade of the vital trade waterway.

Tehran has loaded about 260,000 barrels of oil per day for export at its ports so far this month, which is a decline of more than 80% compared to the 1.7 million bpd in August 2025, CNBC reported, citing data from the trade intelligence firm Kpler.

On July 14, Trump reimposed the blockade in retaliation for Iran attacking oil tankers transiting the strait. Iran's crude exports are down 70% in August from 893,000 bpd last month.

The exports are a crucial revenue stream for Iran, and the Trump administration says the blockade will decimate the country's economy, forcing it to capitulate to U.S. demands, Bob McNally, president of Rapidan Energy, told CNBC.

1787923526423.png


America's next grocery shock is brewing​

https://www.axios.com/2026/08/30/grocery-inflation-prices-war-diesel

America's grocery squeeze has thus far been most painfully felt in a few expensive categories, like beef, coffee and chocolate.

  • Now, the forces pushing up food prices are starting to pile up: expensive grain, soaring fertilizer and fuel, plus unpredictable weather and raging wars.
Why it matters: The next grocery price shock could hit much harder — and much wider.


The big picture: Your grocery store is fed by a vast global supply chain, and pressures are building all along it.

  • The Iran and Russia-Ukraine wars have driven up diesel prices, making it more expensive to operate farm equipment for harvesting and to truck food from suppliers to stores.
  • The war in Iran has also disrupted fertilizer supply and price, as a large share of the world's fertilizer passes through the Strait of Hormuz.
  • Corn and wheat prices are surging, this week hitting their highest level in three years. Bad weather has hit corn crop yields, and the Russia-Ukraine war has roiled wheat exports.
Friction point: Wheat's a key ingredient in pantry staples and corn is a major animal feed, so as they go up, so can meat, dairy and eggs.

The intrigue: Don't assume those soaring commodity prices are a bonanza for farmers, either.

  • They're still getting squeezed by all the other crises. Even the president of the National Corn Growers Association toldAxios Future of Energy author Ben Geman that he himself wouldn't be profitable this year.
Add all these pressures to the list of already inflated food items:

  • Instant coffee is up 15.8% year-over-year; tomatoes, 12.8%; beef roasts, 13.5%; apples, 11.1%.
  • In the latest Economist/YouGov poll, about three-quarters of people said grocery prices are still rising where they live.
Threat level: There's reason to believe it's only going to get worse.

  • In a widely cited report earlier this month, J.P. Morgan analysts warned that global food inflation would hit 5% in the first half of 2027, nearly double what it was in the first half of 2026.
  • "Price pressures are expected to extend through (the first half of 2027), as crop and price effects are still building and agricultural impacts lag the oceanic peak by 6 to 12 months," they wrote.
The bottom line: These forces don't drive up your grocery budget overnight, but the compounding strain on the cost of growing, harvesting and transporting food is poised to make an already expensive grocery run even worse.
 
America's next grocery shock is brewing
Wait, isn't that old news??

The Panicans were saying that was going to happen months ago, like back in April? What happened?

about three-quarters of people said grocery prices are still rising where they live.
Inflation is a thing. Haven't prices been rising like, forever, because of inflation and people wanting to make higher wages? Certainly longer than any of us have been on this rock.
 
Wait, isn't that old news??

The Panicans were saying that was going to happen months ago, like back in April? What happened?


Inflation is a thing. Haven't prices been rising like, forever, because of inflation and people wanting to make higher wages? Certainly longer than any of us have been on this rock.
Some prices rise. Some prices rise higher than other prices for differing items. Some prices stay relatively flat. Some prices fall. There isn't just inflation, deflation is a thing, too, but there are no guarantees it will last long term.

Recently, a local WalMart Supercenter just started stocking 20 pound bags of dry pinto beans at $14.94/bag (~$0.75/lb). That's the lowest price for dry beans that I've seen in roughly a decade. I've also seen 1 pound bags of some dry beans at over $4.00/lb. I choose buying the 20 lb bags. Since those expensive 1lb bags are also on the shelves, I'll guess that other consumers are making that choice.

There are things that I never expect to inflate back to their all-time highs. Like one Semper Augustus tulip bulb, said to be worth about 10 years salary of a skilled craftsman, at the peak of tulip mania. That was 389 years ago. There could be some inflation in next year's tulip bulb prices, with fertilizer, diesel and workers' wages possibly rising.
 
RT 08:46


Oil Traders Just Got the Worst News Yet​


Eckard Enterprises | Oil & Gas Investing
7.65K subscribers


Aug 31, 2026

Oil prices are going higher for longer. The Strait of Hormuz crisis has no endgame, and crude oil supply cannot catch up. Troy W. Eckard explains why $86 a barrel is the floor, not the ceiling, and what one blip in the Middle East could do to energy markets.
Contact us: https://lp.eckardenterprises.com/?utm...

In this video he explains:

0:00 Strait of Hormuz Conflict and Oil Prices
0:48 Why $86 Oil Could Continue Rising
1:45 Can Global Producers Replace Lost Supply?
2:39 The War Premium Added to Crude Oil
3:38 Why Oil Supply Data Is So Unclear
4:53 Inflation, Recession, and Energy Costs
6:08 The Lack of a Clear Endgame in Iran
7:19 Why Higher Oil Prices May Last Longer
8:05 Could Oil Jump Another $25 to $50 Per Barrel?
Traders are still being told the war is nearly settled.
The market data says otherwise.

__What You'll Learn on This Channel: Eckard Enterprises shares videos that help accredited investors evaluate opportunities in the energy sector, covering mineral rights, royalties, working interest, oil and gas investing, and tax-advantaged strategies for accredited investors. Topics include market trends, energy sector economic outlooks, and expert discussions featuring industry veteran Troy W. Eckard, Founder and Chairman of the Board of Eckard Enterprises.

===
.
 
Oil prices are going higher for longer. The Strait of Hormuz crisis has no endgame, and crude oil supply cannot catch up. Troy W. Eckard explains why $86 a barrel is the floor, not the ceiling, and what one blip in the Middle East could do to energy markets.
So, a guy who sells oil and gas ownership, is saying oil is going higher. Gee... what are the odds...

Directly Own Oil and Gas Assets​


We help accredited investors own oil & gas assets in their portfolios. We believe in the value of owning assets that grow in value while generating decades of cash flow from products that the world consumes daily.
 
day after day another supertanker gets bombed.

Projectiles Hit Two Supertankers Exiting Hormuz As Brent Tops $92, Diesel Crack Breaches $100​


Via ZeroHedge

Two oil supertankers were struck by unknown projectiles
while transiting the Strait of Hormuz early Tuesday, signaling yet another sharp escalation in hostilities along the world’s most critical energy chokepoint.

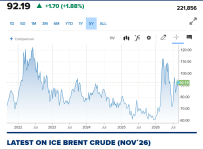
The attacks follow President Trump’s warning Monday that additional strikes against Iran remain possible. Traders are pricing in a further war risk premium, pushing Brent crude futures above $92 a barrel, while US diesel crack spreads have breached the critical $100-a-barrel threshold.

Maritime security consultant Marisks reports that Saudi shipping giant Bahri’s VLCC Sidr was hit northeast of Khasab, Oman. The Sinokor-operated Senegal Prosperity was reportedly struck by three projectiles farther east. Both tankers were exiting the maritime chokepoint.

UK Maritime Trade Operations separately confirmed that a tanker completing an outbound transit of Hormuz reported three projectile strikes but did not identify the vessel.


Brent crude futures ripped higher during Asian and European trading on the news, with the benchmark firmly above $92 as of 0600 ET.


President Donald Trump warned Monday that further strikes are possible, pushing Brent back above $91/bbl and driving another bear-steepening move across global bond markets,” UBS analyst George Redman wrote earlier.

US diesel crack spreads were above $100 as of 0600 ET.


As we’ve extensively detailed, the energy crisis is not necessarily in crude itself but in refined products. Gulf diesel and gasoline shipments have declined amid disruptions in the Strait of Hormuz, while damage to Russian energy infrastructure from Ukrainian one-way attack drones has created a perfect storm in global refining markets in late summer.

Goldman’s energy expert Daan Struyven warned in his most recent note that “diesel is at the epicenter of the supply squeeze.”

Rising strikes on refineries in the Middle East and Russia have further constrained already-stretched global refining capacity, pushing refined-products margins to new highs,” Struyven and Yulia Zhestkova Grigsby wrote in the note, adding, “Diesel remains at the epicenter of the rally.”

Struyven and his team estimate that global refinery runs are down 7 million barrels per day from last year and have averaged nearly 6 million barrels per day below seasonal norms since March, around the time the US launched Operation Epic Fury and Ukraine ramped up one-way drone attacks against Russia’s energy infrastructure.


Meanwhile, there may be some diplomatic traction in the Gulf area, with Iranian President Masoud Pezeshkian saying on state TV: “I state unequivocally that should the US return to its commitments under the aforementioned Memorandum of Understanding, the Islamic Republic of Iran will also take reciprocal action immediately.”

Treasury Secretary Scott Bessent’s “Operation Economic Outcast” is also ramping up as the Trump administration deploys sanctions to pressure Tehran into submission.
 
Brent crude futures ripped higher during Asian and European trading on the news, with the benchmark firmly above $92 as of 0600 ET.
I'm still trying to figure out, why we haven't seen the $150 - $200 a barrel, that was predicted during the start of the military operation? Why hasn't that happened?

It hasn't even reach the level back in 2022, when there was NOTHING going on, except Biden trying to win the mid-terms.. Certainly, a military operation and bombing is more serious than a election, right?

1788273972834.png
 
Not just the price of oil, but the cost for transporting it. Charting at site.


Breakwave Wet Freight Futures Index​

The Index is designed to track the oil tanker market through freight futures contracts with a weighted average maturity of approximately 60-70 days and a sector weighting of 90% TD3C VLCC contracts and 10% TD20 Suezmax contracts.


Intraday1w1m3m1y5yYTDMax
Index comparison


Master data
ISINDE000SL0HLG3
WKNSL0HLG
RIC.BWETFF
Bloomberg tickerBWETFF
Return TypeExcess Return
CurrencyUSD
Current quotes
Last quote9654.90
Last updateas of 01 Sep 2026 at 16:33:19 CET
Day rangeLow: 9654.90, High: 9654.90
Daily changeAbsolute: -16.15, Percentage: -0.17%
Year rangeLow: 1347.39, High: 10597.26
Please note that the index chart above may be partly comprised of historical performance illustration based on a backtest. The guideline provides an indication where this is the case.

Spot vs. Contract Price: Tanker freight rates are quoted in US dollars per metric ton and reflect underlying spot market averages.
 
So, a guy who sells oil and gas ownership, is saying oil is going higher. Gee... what are the odds...

Directly Own Oil and Gas Assets​


We help accredited investors own oil & gas assets in their portfolios. We believe in the value of owning assets that grow in value while generating decades of cash flow from products that the world consumes daily.
Earlier you had issue with someone questioning nond rates from that was with Goldman Sachs. Interesting selective perspective.
 
I'm still trying to figure out, why we haven't seen the $150 - $200 a barrel, that was predicted during the start of the military operation? Why hasn't that happened?

It hasn't even reach the level back in 2022, when there was NOTHING going on, except Biden trying to win the mid-terms.. Certainly, a military operation and bombing is more serious than a election, right?

View attachment 618954
Ask Peter Schiff, who predicted $200/barrel oil back in 2008. ;)
 
Hope everyone is enjoying higher food prices. Likely your reality for the foreseeable future due to the Iran War.

Why higher fertilizer prices are here to stay

Why higher fertilizer prices are here to stay

Key points​

  • Unlike the 2022 fertilizer shock, the reasons behind today’s disruption are longer lasting. Geopolitical conflicts and supply chain disruptions will keep fertilizer prices elevated and complicate future sourcing for agricultural retailers and farmers.
  • Fertilizer prices, particularly for phosphate products, are projected to rise and remain above pre-Iran war levels through 2028. Ammonia and sulfur are the two biggest variable cost inputs for phosphate production, and 3 of the 10 world’s largest ammonia exporters are behind the Strait of Hormuz.
  • Farmers have reduced phosphate and potassium applications by as much as 10%-15% in recent years, a pattern that may modestly support commodity prices and ease inventory concerns for retailers.
Fertilizer prices have come down from their historic highs following the start of the Iran war; however, the ripple effect of the Middle East conflict compounded with tight supplies will create higher prices and sourcing issues in 2027 and beyond. Availability and affordability concerns have created demand destruction and demand deferral that cloud the fertilizer price outlook for the next few years. Market recovery depends on stabilization in the Middle East, sulfur price trends and shifts in global demand patterns.

Unlike the 2022 fertilizer shock, today’s disruption is rooted less in rerouted trade flows and more in damaged production capacity, raw material constraints and uncertain recovery timelines. That makes this a longer-duration risk for U.S. agricultural retailers, who must secure enough supply for farmers without overcommitting to high-priced inventory if demand weakens.

The fertilizer price run-up in 2022 stemming from the Ukraine war forced a reshuffling of the flow of fertilizer products. The current conflict in the Middle East has resulted in shutdowns and damage that will require significant time and resources to restart, long after the war has concluded. An estimated 31 ammonia plants in the Middle East have been directly impacted by the conflict or have shut down production completely. Also, 49 plants in India, Pakistan and Bangladesh are either curtailed or shut down due to constrained feedstock. Lastly, at least 20 plants in Russia have been damaged from Ukrainian drone attacks.

The Middle East plays a critical role in the international fertilizer market, supplying over 60 million tons of fertilizers and raw materials worldwide, with 45 million tons shipped via the Strait of Hormuz. Notably, 50% of globally traded sulfur and over 30% of global urea exports originate from this region, making these commodities particularly vulnerable to supply disruptions.

Farmers have reduced application rates​

Most farmers have already adjusted fertilizer management in response to elevated prices over the past several years. Rather than dramatically reducing application rates, they have relied heavily on soil analysis, variable-rate technologies and better nutrient management to optimize returns. Under-fertilization can be more costly than higher fertilizer prices as it directly reduces crop productivity, in turn increasing the cost of production per unit of output — which is why many U.S. farmers have not pulled back on nitrogen applications.

However, farmers have reduced phosphate and potassium application levels by as much as 10%-15% in recent years. Since 2008, farmers have reduced NPK (nitrogen, phosphorus and potassium) applications by 20%. Lower and no fertilizer use creates a two-to-three-year gap before yield losses appear, raising the question of how much longer growers can mine soil nutrients without sacrificing yield. Cash is tight at the farm gate, limiting some growers from locking in any product for the next crop year until additional financing or working capital becomes available.

North Dakota State University projected fertilizer prices to continue to rise and then see a prolonged plateau that remains above pre-Iran war levels until 2028. NDSU projects 2027 averages for fertilizer at $496 for urea, $666 for DAP, $660 for MAP, $619 for ammonia, and $361 for UAN. These estimates are lower than NDSU’s estimates in the spring following the conflicts’ greatest surge in prices but still forecast higher prices than pre-war levels.
 
Hope everyone is enjoying higher food prices. Likely your reality for the foreseeable future due to the Iran War.

Why higher fertilizer prices are here to stay

Why higher fertilizer prices are here to stay

Key points​

  • Unlike the 2022 fertilizer shock, the reasons behind today’s disruption are longer lasting. Geopolitical conflicts and supply chain disruptions will keep fertilizer prices elevated and complicate future sourcing for agricultural retailers and farmers.
  • Fertilizer prices, particularly for phosphate products, are projected to rise and remain above pre-Iran war levels through 2028. Ammonia and sulfur are the two biggest variable cost inputs for phosphate production, and 3 of the 10 world’s largest ammonia exporters are behind the Strait of Hormuz.
  • Farmers have reduced phosphate and potassium applications by as much as 10%-15% in recent years, a pattern that may modestly support commodity prices and ease inventory concerns for retailers.
Fertilizer prices have come down from their historic highs following the start of the Iran war; however, the ripple effect of the Middle East conflict compounded with tight supplies will create higher prices and sourcing issues in 2027 and beyond. Availability and affordability concerns have created demand destruction and demand deferral that cloud the fertilizer price outlook for the next few years. Market recovery depends on stabilization in the Middle East, sulfur price trends and shifts in global demand patterns.

Unlike the 2022 fertilizer shock, today’s disruption is rooted less in rerouted trade flows and more in damaged production capacity, raw material constraints and uncertain recovery timelines. That makes this a longer-duration risk for U.S. agricultural retailers, who must secure enough supply for farmers without overcommitting to high-priced inventory if demand weakens.

The fertilizer price run-up in 2022 stemming from the Ukraine war forced a reshuffling of the flow of fertilizer products. The current conflict in the Middle East has resulted in shutdowns and damage that will require significant time and resources to restart, long after the war has concluded. An estimated 31 ammonia plants in the Middle East have been directly impacted by the conflict or have shut down production completely. Also, 49 plants in India, Pakistan and Bangladesh are either curtailed or shut down due to constrained feedstock. Lastly, at least 20 plants in Russia have been damaged from Ukrainian drone attacks.

The Middle East plays a critical role in the international fertilizer market, supplying over 60 million tons of fertilizers and raw materials worldwide, with 45 million tons shipped via the Strait of Hormuz. Notably, 50% of globally traded sulfur and over 30% of global urea exports originate from this region, making these commodities particularly vulnerable to supply disruptions.

Farmers have reduced application rates​

Most farmers have already adjusted fertilizer management in response to elevated prices over the past several years. Rather than dramatically reducing application rates, they have relied heavily on soil analysis, variable-rate technologies and better nutrient management to optimize returns. Under-fertilization can be more costly than higher fertilizer prices as it directly reduces crop productivity, in turn increasing the cost of production per unit of output — which is why many U.S. farmers have not pulled back on nitrogen applications.

However, farmers have reduced phosphate and potassium application levels by as much as 10%-15% in recent years. Since 2008, farmers have reduced NPK (nitrogen, phosphorus and potassium) applications by 20%. Lower and no fertilizer use creates a two-to-three-year gap before yield losses appear, raising the question of how much longer growers can mine soil nutrients without sacrificing yield. Cash is tight at the farm gate, limiting some growers from locking in any product for the next crop year until additional financing or working capital becomes available.

North Dakota State University projected fertilizer prices to continue to rise and then see a prolonged plateau that remains above pre-Iran war levels until 2028. NDSU projects 2027 averages for fertilizer at $496 for urea, $666 for DAP, $660 for MAP, $619 for ammonia, and $361 for UAN. These estimates are lower than NDSU’s estimates in the spring following the conflicts’ greatest surge in prices but still forecast higher prices than pre-war levels.
I'm just a small-time gardener. I stocked up with fertilizer, at the start of the war buildup by the Navy, for the next two years.
 

Global bond sell-off intensifies as US-Iran tensions stoke inflation fears​

Global bond sell-off intensifies as US-Iran tensions stoke inflation fears

The global government bond sell-off resumed on Wednesday, driving up the UK’s borrowing costs and exacerbating the challenges facing John Healey as he prepares his first budget.

The yield – effectively the interest rate – on 10-year UK government bonds, or gilts, jumped to just below 5.3% in early trading: its highest level since mid-2008.

Investors across major markets have been dumping bonds in recent days amid fears about inflation and spiralling deficits.

Global inflation fears have intensified since the US and Iran began exchanging fire again at the weekend, pushing up the oil price and increasing expectations that central banks will have to raise interest rates in the coming months.

Higher bond yields progressively increase the cost of financing the government’s debt. UK analysts have warned that higher gilt yields since the start of the Iran war have potentially wiped out almost half of Healey’s headroom against the government’s fiscal rules.

Economists at Deutsche Bank reckon the £26bn room for manoeuvre Rachel Reeves created at her spring forecast could be down to less than £14bn by the time of the 28 October budget.

Healey would then have to decide whether to rebuild the margin for error with tax increases or spending cuts – alongside facing pressure to fund higher defence spending.

Chris Beauchamp, the chief market analyst at IG, said: “Governments around the world are feeling the pressure from bond markets, but the situation is particularly acute for the UK, where Andy Burnham’s grand promises about reforming the economy are about to meet the cold reality of high debt levels and rocketing borrowing

The Brent crude oil benchmark is currently hovering at about $95 a barrel amid renewed fighting in the Middle East. The US launched new airstrikes on Iranian targets overnight, prompting counterstrikes by Tehran targeting American interests in Gulf allies.

The resumption of the sell-off in UK markets came after Asian stock markets fell sharply. In Tokyo the Nikkei 225 share index slumped by 2.85%. China’s CSI 300 lost 1.4%, while South Korea’s Kospi dropped by 3.3%.

Investors have also been rattled in recent days by the US administration’s attempts to interfere in financial markets – including helping the Japanese to prop up the value of the yen and buying back more US government bonds, or treasuries, to rein in rising yields. Neither move appears to have been successful.
 

Maybe you should give a call to your buddies in Russia and Ukraine, and tell them to stop blowing up oil infrastructure and refineries... so more diesel flows....

Then, give a call to your buddy Mullahs in Iran, and tell them to stop blowing up refineries of all their neighbors in the gulf, so they can refine diesel, and so you don't have to pay $10 a gallon for diesel in New Zealand.

1788386304644.png

Diesel.jpg
 

There Are Four Forces Pressuring Bonds: War Is No. 1

https://www.wsj.com/finance/investing/there-are-four-forces-pressuring-bonds-war-is-no-1-68d3ace9

Worries about runaway government spending. A new Federal Reserve chairman. The huge surge in bond issuance to fund the artificial-intelligence build-out. There are many forces pushing Treasury yields higher. But the main driver of the recent run-up: inflation.

While a confluence of factors has powered the global bond slide that carried yields to multiyear highs around the world, a look inside market shifts suggests the key factor in this country remains the sharp climb in energy prices driven by the war in Iran.

“The sharp rise in global bond yields reflects investors reassessing inflation,” said Mike Goosay, chief investment officer and global head of fixed income at Principal Asset Management.

Here is a look at the key factors:

Fuel prices​

Diesel prices have surged this summer since the U.S.-Iran ceasefire fizzled and Ukraine began a campaign to knock out refineries in Russia, which is a major exporter of the fuel. Rising diesel prices tend to be more inflationary than those for gasoline since it is burned by trucks, trains, construction equipment and farming implements, lifting the cost of producing and shipping all manner of goods.

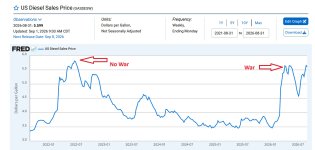
U.S. national average retail prices for diesel exceeded $5.68 a gallon on Wednesday, about $2 higher than a year ago, according to Dow Jones Energy. The price is less than a penny shy of the high hit this spring after fighting began in the Persian Gulf and hindered transit through the Strait of Hormuz and within 13 cents of the record set in 2022 after Russia invaded Ukraine.

Futures trading points to higher prices at the pump down the road. Diesel futures for October delivery have risen roughly 13% over the past week.

Deficits​

It isn’t just inflation driving yields higher. Some investors also cited concerns over out-of-control government spending.

Gross U.S. debt surpassed $40 trillion for the first time last month, a milestone that only amplified the chorus of economists warning that America is on an unsustainable fiscal trajectory. Publicly-held U.S. debt as a share of gross domestic product is fast approaching levels not seen since World War II.

Overseas, soaring government bond yields in the U.K. have forced the government to try to cut its debts. And Japan’s 10-year government bond yield just hit the highest level in about 30 years amid a debate over tax cuts that could weaken Japan’s fiscal position.

Term premium​

One place investors’ worries about fiscal policy or the growing supply of bonds would be evident is the term premium, typically defined as the component of Treasury yields that reflects everything other than investors’ expectations for short-term interest rates set by the Federal Reserve.

That has climbed recently. But the biggest change has come since the start of the Iran war, and some investors and economists note that term premiums are higher in Europe and Japan, signaling more worry about the fiscal situation overseas.

Interest-rate bets​

Fed Chairman Kevin Warsh’s Jackson Hole speech in late August alleviated some worries the Fed was insufficiently committed to fighting inflation, helping spark the climb in yields.

Still, Warsh has eschewed offering forward guidance like his predecessors, and the increased uncertainty is likely getting baked into longer-term borrowing costs in the U.S. and around the world, said David Kelly, chief global strategist at J.P. Morgan Asset Management.

“If you have to identify one thing that’s distinctly different from a few months ago, I do think it’s the behavior of the Federal Reserve since Kevin Warsh took over,” Kelly said. “I think there has been a Fed risk premium, even if it’s a small one, added to markets.”

Meanwhile, the effects of Treasury Secretary Scott Bessent’s plan to buy back more longer-term bonds have been short-lived. “If the government says it’s going to raise taxes and cut spending to bring the deficit down, that’s one thing,” Kelly added. “Saying you found another credit card that you haven’t maxed out in your stack of 20 doesn’t actually inspire confidence.”
 
Status
Not open for further replies.
Top