Ben Sunday
Has No Life - Lives on TB
I'm not a finance guru but certainly share the concerns expressed here.

Some seem to be able to if it fits the narrative.It does not feel the same because it is not the same.
Servicing the current US debt at say for example 5% today is not remotely the same as servicing the US debt at 5% 20 year ago because the debt servicing costs have exploded in the last few years. This is why you cannot look at just an interest rate chart in isolation and compare rates today vs 10, 20, or 30 years ago - 5% today has a very different effect than 5% in the past. The US debt situation has radically changed, so the impact of rising interest rates will likely be quite different this time around.
Fiscal Data Explores Interest Expense on National Debt

Ahhh. yes... Now we're back to fiat currency and the US Dollar?View attachment 619139
No way out this time. When you are in vertical inflection of money printing the crash is assured. Just a matter of when. And the bond markets are rumbling like a bad bout of diarrhea is approaching.
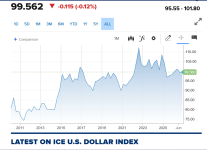

On or before Oct.19th expect a huge selloff. If I am wrong I will jump out the windowPeople keep saying "this time is different". Okay. So stop thinking that fiat currency, bonds, etc. are going to act the same instead of the different everything else is supposed to be.
If things are different then figure out how the results are going to be different as well. Fiat will be different. PMs will be different. Bonds, stocks, all of it will be different. And your thinking needs to be different as well.
Digital currencies already exist (crypto, etc) but that's not what I'm talking about. I'm talking about a completely new currency system for a country, not just a digital currency valued in fiat dollars. A true digial currency system will revalue everything, not revalue it in fiat currency dollars, nor in PMs that are valued in fiat currency dollars. It will be a completely new beastie to deal with.
I don't have all the answers, I certainly don't have the exact timeline. I do know that they have enough to push this years more down the road though everyone struggles to believe that is possible. Given the condition other countries are in and how dependent so many still are on the US being the grease in the wheels of their own economy (from our consumption to our other types of support) I do not see anything more than a potential correction occurring any time over the next year. Collapse is still a ways off.
Don't give into Chicken Little or the pathos of inevitable failure. Before things completely fail, they'll change the game/system. When they do it, don't get caught with you pants down.

Practice your jump and roll to lessen the impact.On or before Oct.19th expect a huge selloff. If I am wrong I will jump out the window
Note1: Don't get too excited...I live on the first floor.

How does one take advantage of this?Every time things happen they are different in some respects. There a number of people who think they are allowing the debt to pack on now so that when they revalue and change to a purely digital currency it will give the US a considerable amount of leverage.
A change in currency is pretty much baked in. Study the history of when various countries left the gold. The US wasn't first by a long shot. We have a perfect storm, we just don't know when it is going to break or what is going to do the breaking.
And then there is the political pressures that groups like the DSA is creating. They have at least as much reason to convert to digital currency as any other entity you can name here in the US.
People need to prepare however they can prepare, just with serious care in case it takes longer to occur than the immediate doomers think. I suspect we still have several binge/purge financial cycles to get through and you need to position yourself to take advantage of them. Not just survive, but take advantage of them. That is going to require a mindset based on facts, not emotions.
Don't worry you won't be jumping-other people possibly? Remember they always tell you what they are going to do before they do it.On or before Oct.19th expect a huge selloff. If I am wrong I will jump out the window
Note1: Don't get too excited...I live on the first floor.

The Obama regime learned how to use the banking system and national debt to pump the markets. There was no "recovery". It was plastic surgery on a dead prune and a robotic mechanism installed to simulate life. Black Rock, Goldman Sachs, JP Morgan Chase, all the tribal players worked their magic tricks with fake money and computer programs while propaganda swept the airwaves.Thank you. Really interesting and FACTUAL article that avoids overemotional claptrap. Short plot explanation:
- S&P 500 corrections are common. Since 1950, the index has experienced around 38 corrections (10%+) and 14 bear markets (20%+).
- Recovery times vary widely. Typical corrections have recovered in 3-8 months, while major bear markets have often taken 1-2 years or longer.
- The deepest post-1950 decline occurred during the 2007-2009 Global Financial Crisis, when the S&P 500 fell 56.8% before recovering in 2013.
- The fastest major recoveries followed the 2020 COVID-19 crash and the 2025 market correction, with the latter reclaiming its previous high in about 89 trading days after a decline exceeding 15%.
- The type of crisis matters. External shocks have historically rebounded faster than systemic financial crises, which typically require longer recoveries.
- History provides context, not certainty. Every post-1950 S&P 500 correction has eventually recovered, but future market performance and recovery timelines are never guaranteed.
Equally as short of an explanation:
What goes up will come down. What goes down will go back up based on historical data and facts. Money can be made going in either direction. So be prepared and stop shaking in your boots.
Personal anecdote:
During 2007/2008 when everyone ran around crying and moaning, hubby and I more than doubled our business and set ourselves up for two decades and beyond of financial success. During the 2019/2020 Covid fiasco, we made a tidy sum as well by having already paid off our debt and prepositioned ourselves to take advantage of other people's failures.
Historical anecdotes and facts:
Most of the "new wealth" post the Great Depression came about as a result of people taking advantage of opportunities offered during that financial era. Corrections can be gifts, you just have to keep your eyes open.
Here's a funny one from Florida:

The Obama regime learned how to use the banking system and national debt to pump the markets. There was no "recovery". It was plastic surgery on a dead prune and a robotic mechanism installed to simulate life. Black Rock, Goldman Sachs, JP Morgan Chase, all the tribal players worked their magic tricks with fake money and computer programs while propaganda swept the airwaves.
Same for the COVID schemes. Many devils got rich in these events. Nothing new under today's sun, except the approaching reset timing. The lockdown is almost in place and your monitors are coming along nicely. All will be watched and your privacy will become illegal.
OK, so that's not a problem with the bond market, because we've seen these rates before.It's not that interest rates haven't been this high before but the credit environment was different. We have a number of different entities that need to roll debt over. Debt that was initiated at much lower rates. This includes the AI/technology entities, private credit/equity, and mortgages (both commercial and residential).

In the derivative market, Interest rate derivatives are a large part of the notional value, because the Bond market itself is so large. THAT is where the risk is.OK, so that's not a problem with the bond market, because we've seen these rates before.
Isn't that the fault of those borrowers/lenders, who didn't calculate that there might be a change in rates, by the time they had to roll over debt?
On or before Oct.19th expect a huge selloff. If I am wrong I will jump out the window
Note1: Don't get too excited...I live on the first floor.

But there are those who love the Beast system and will defend it unto their own death……though they claim a different following/motivation…….
Very few of us want to live in the woods, without electricity, and eat bugs..But there are those who love the Beast system and will defend it unto their own death……though they claim a different following/motivation…….
Bessant....Soro's partner were rock and rolling the currency markets for big time profits. What comes around goes around.Don't worry you won't be jumping-other people possibly? Remember they always tell you what they are going to do before they do it.
Scott Bessent quote " Why would I want to blow up the global financial system?" ;-)
Of course it is! However the last time that happened (2008), they got bailed out except for Bear-Stearns and Lehman Brothers. Laws had been broken but no one went to jail. And everyone else gets to pay for it by increasing the federal deficit and unstable valuations in the stock market and housing market. The derivatives market is also much higher. That magnifies the risk.Isn't that the fault of those borrowers/lenders, who didn't calculate that there might be a change in rates, by the time they had to roll over debt?

I’m still rocking the one month T Bill and chill for the liquidity side of the house, and rates are still close to 4.I, for one, like the 10 year at a higher rate... It makes CD rates higher and High Yield Savings rates higher... Good for me...
Imagine the top tier Camaro in 82 cost 9000 dollars, now it costs close to 90,000 dollars. There is a message there, somewhere…What was the National Debt in 1982?
Summerthyme
You darn heretic!Very few of us want to live in the woods, without electricity, and eat bugs..
So, we learned how to work the "system" to our advantage, and have a 21st century lifestyle.


My grandson just ask me what it was like growing up in the 1900s.I’m still rocking the one month T Bill and chill for the liquidity side of the house, and rates are still close to 4.
Imagine the top tier Camaro in 82 cost 9000 dollars, now it costs close to 90,000 dollars. There is a message there, somewhere…
You darn heretic!
However, I grudgingly must admit at 68, I really do enjoy things like A/C, and much of the rest of what the 21st Century has to offer…
I was ready for the big red button to be pushed for decades, now not so much…
Unfortunately, the time for this runaway train to have been fixed has long passed—with minimal pain of course.
No one knows the day or the time, but we are definitely in the season….
And I do appreciate everyone’s perspective…..
That 90K Camaro(2027 Z-28) you speak of is quite a bit more than the 1982 Camaro. In every way. 5.4L flat plane crank V-8, 535hp, 505lbft of torque in a chassis that can handle it. the 1982 example is quite pedestrian as a comparison.Imagine the top tier Camaro in 82 cost 9000 dollars, now it costs close to 90,000 dollars. There is a message there, somewhere…


And that amount of gold was not taxed as income when you stacked it in 1982. The funds at the time where already taxed as you earned it back then.Yep, I know that Fed measure of discounting inflation.
You know what’s even weirder? Spend the same amount in 1982 on gold instead of a Camaro and you’d have 108,000 dollars today.
Wow, gold did all that without any hedonic quality adjustment. Isn’t that funny….
Just to be clear, I’d love to have an SS Chevelle with three in the tree. But I’d have to go back a little further in time….
That reminds me of the home purchase conversation, and why kids can't buy a starter home now. No one compares what a starter home was back in 1990, to what a kid thinks his starter home should be now, BIG DIFFERENCE (900 sq. ft versus 2400 sq. ft.).... An apples to hammers comparison. But they just use the price, as a comparison...That 90K Camaro(2027 Z-28) you speak of is quite a bit more than the 1982 Camaro. In every way. 5.4L flat plane crank V-8, 535hp, 505lbft of torque in a chassis that can handle it. the 1982 example is quite pedestrian as a comparison.
But my point was, people are blaming the current rate, as the issue why the bond market will blow up. But the rate is reaching a historical normal. They DON'T want to look at what they did years ago, as the reason why a 5% rate will blow them up.Of course it is! However the last time that happened (2008), they got bailed out except for Bear-Stearns and Lehman Brothers. Laws had been broken but no one went to jail. And everyone else gets to pay for it by increasing the federal deficit and unstable valuations in the stock market and housing market. The derivatives market is also much higher. That magnifies the risk.
I agree with you on that.That reminds me of the home purchase conversation, and why kids can't buy a starter home now. No one compares what a starter home was back in 1990, to what a kid thinks his starter home should be now, BIG DIFFERENCE (900 sq. ft versus 2400 sq. ft.).... An apples to hammers comparison. But they just use the price, as a comparison...

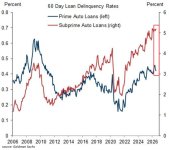
One big piece of the pricing component, comes from the financing end. Remember, on both of those, cars and houses, people buy "Payments", not the actual item. Then, add all upgraded "bells and whistles" in each one... It all has an affect.I agree with you on that.
Cars are SO MUCH Better. Homes are SO MUCH bigger. But either does explain much of the price increase.

Um. Law of supply & demand? Dearth (shortage) of buyers causes sellers to LOWER prices to attract a buyer?What drives interest rates higher is a dearth of buyers in the bond market.