ECON FUNG ORANGE ALERT: 10 Year Bond Rate Hits 4.81%

Once above 5% we are in stock market CRASH TERRITORY...this is MY OPINION..
so do your own DD BEFORE ACTING.

My opinion is that a huge market correction is rearing its ugly head.

Note1: I am the messenger...NOT THE MESSAGE!

10-year U.S. Treasury yield hits highest level since November 2023 as global bond sell-off continues​

Published Wed, Sep 2 20265:14 AM EDT
 

Bonds Beyond Bessent’s control​

Treasury Secretary Bessent tried to beat Mr Market by suppressing bond yields. He should know that it can’t be done, and it is being proved not possible yet again.​

ALASDAIR MACLEOD
SEP 02, 2026
∙ PAID


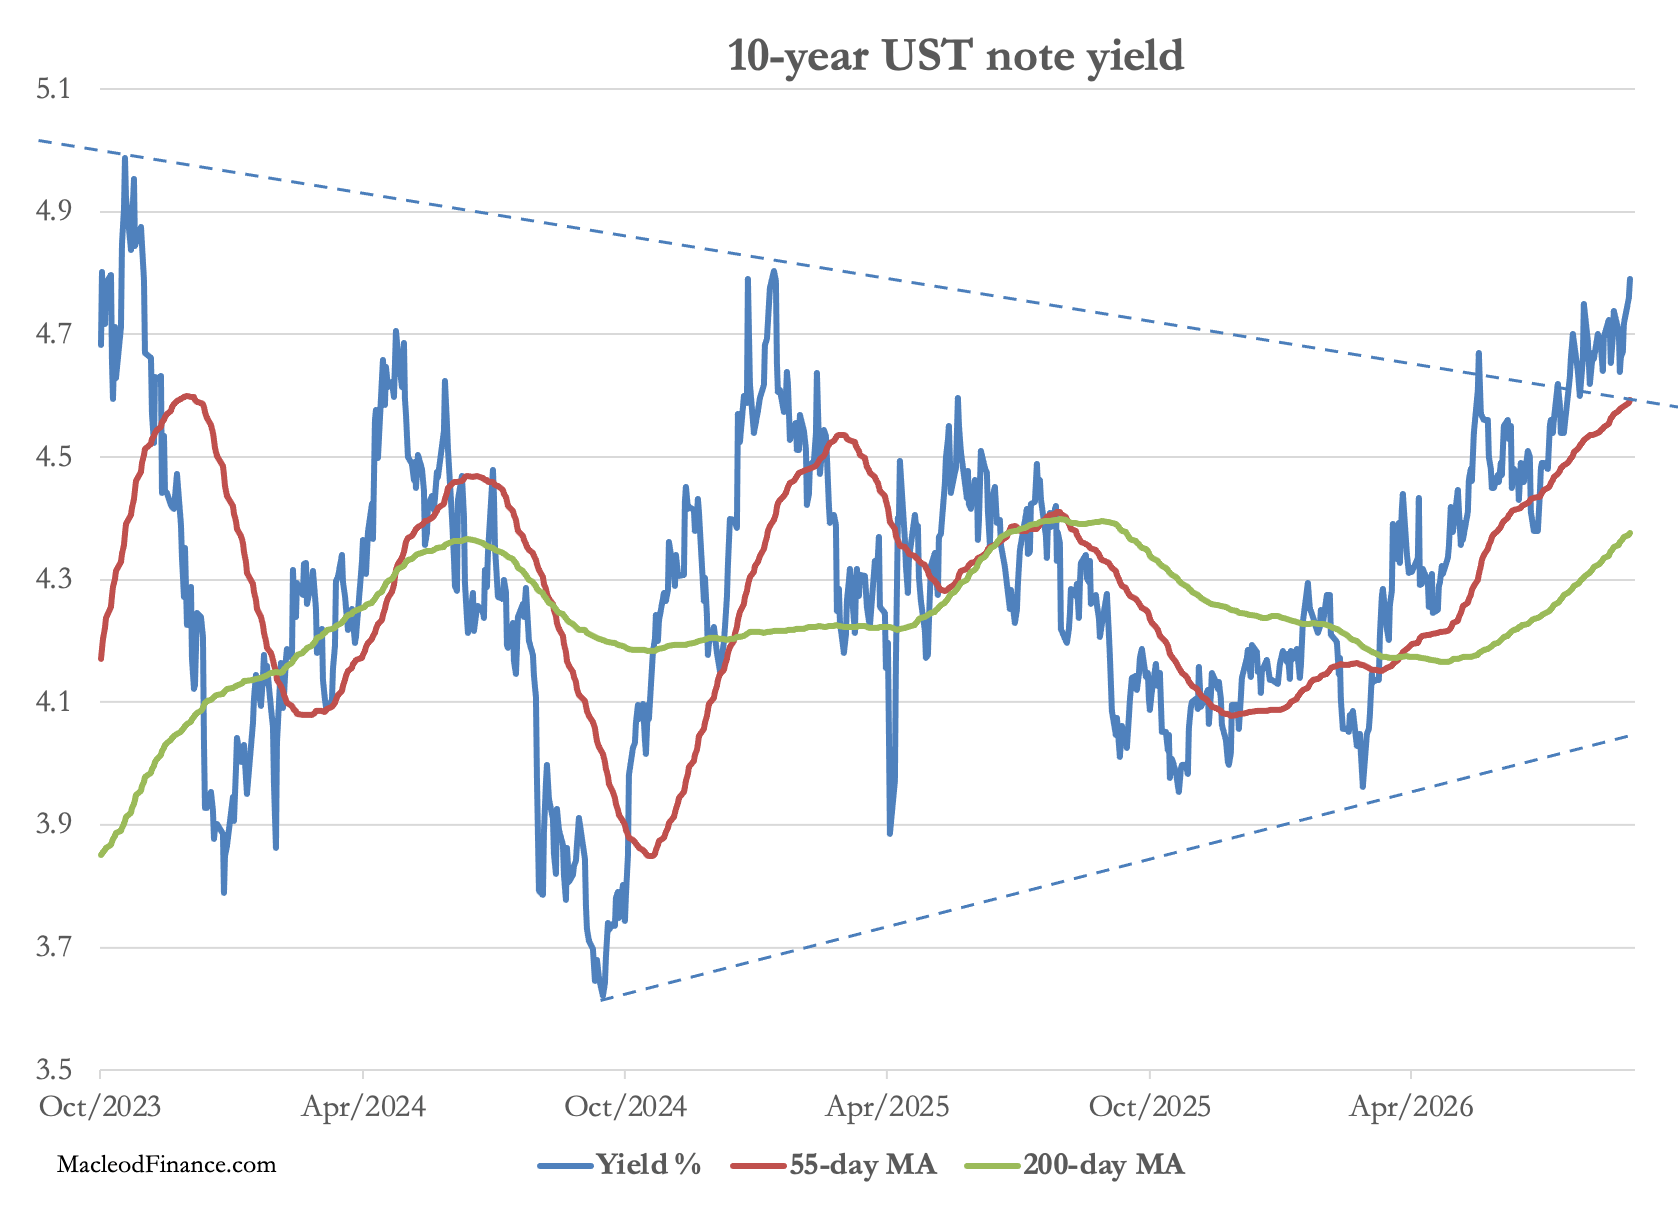
In recent days, the yield on the 10-year US treasury note has broken out above its three-year consolidation phase, confirmed by its short- and longer-term moving averages in bullish sequence: that is to say, bearish for the price. This is despite Bessent’s intervention at the 4.7% yield level on the 10-year note.


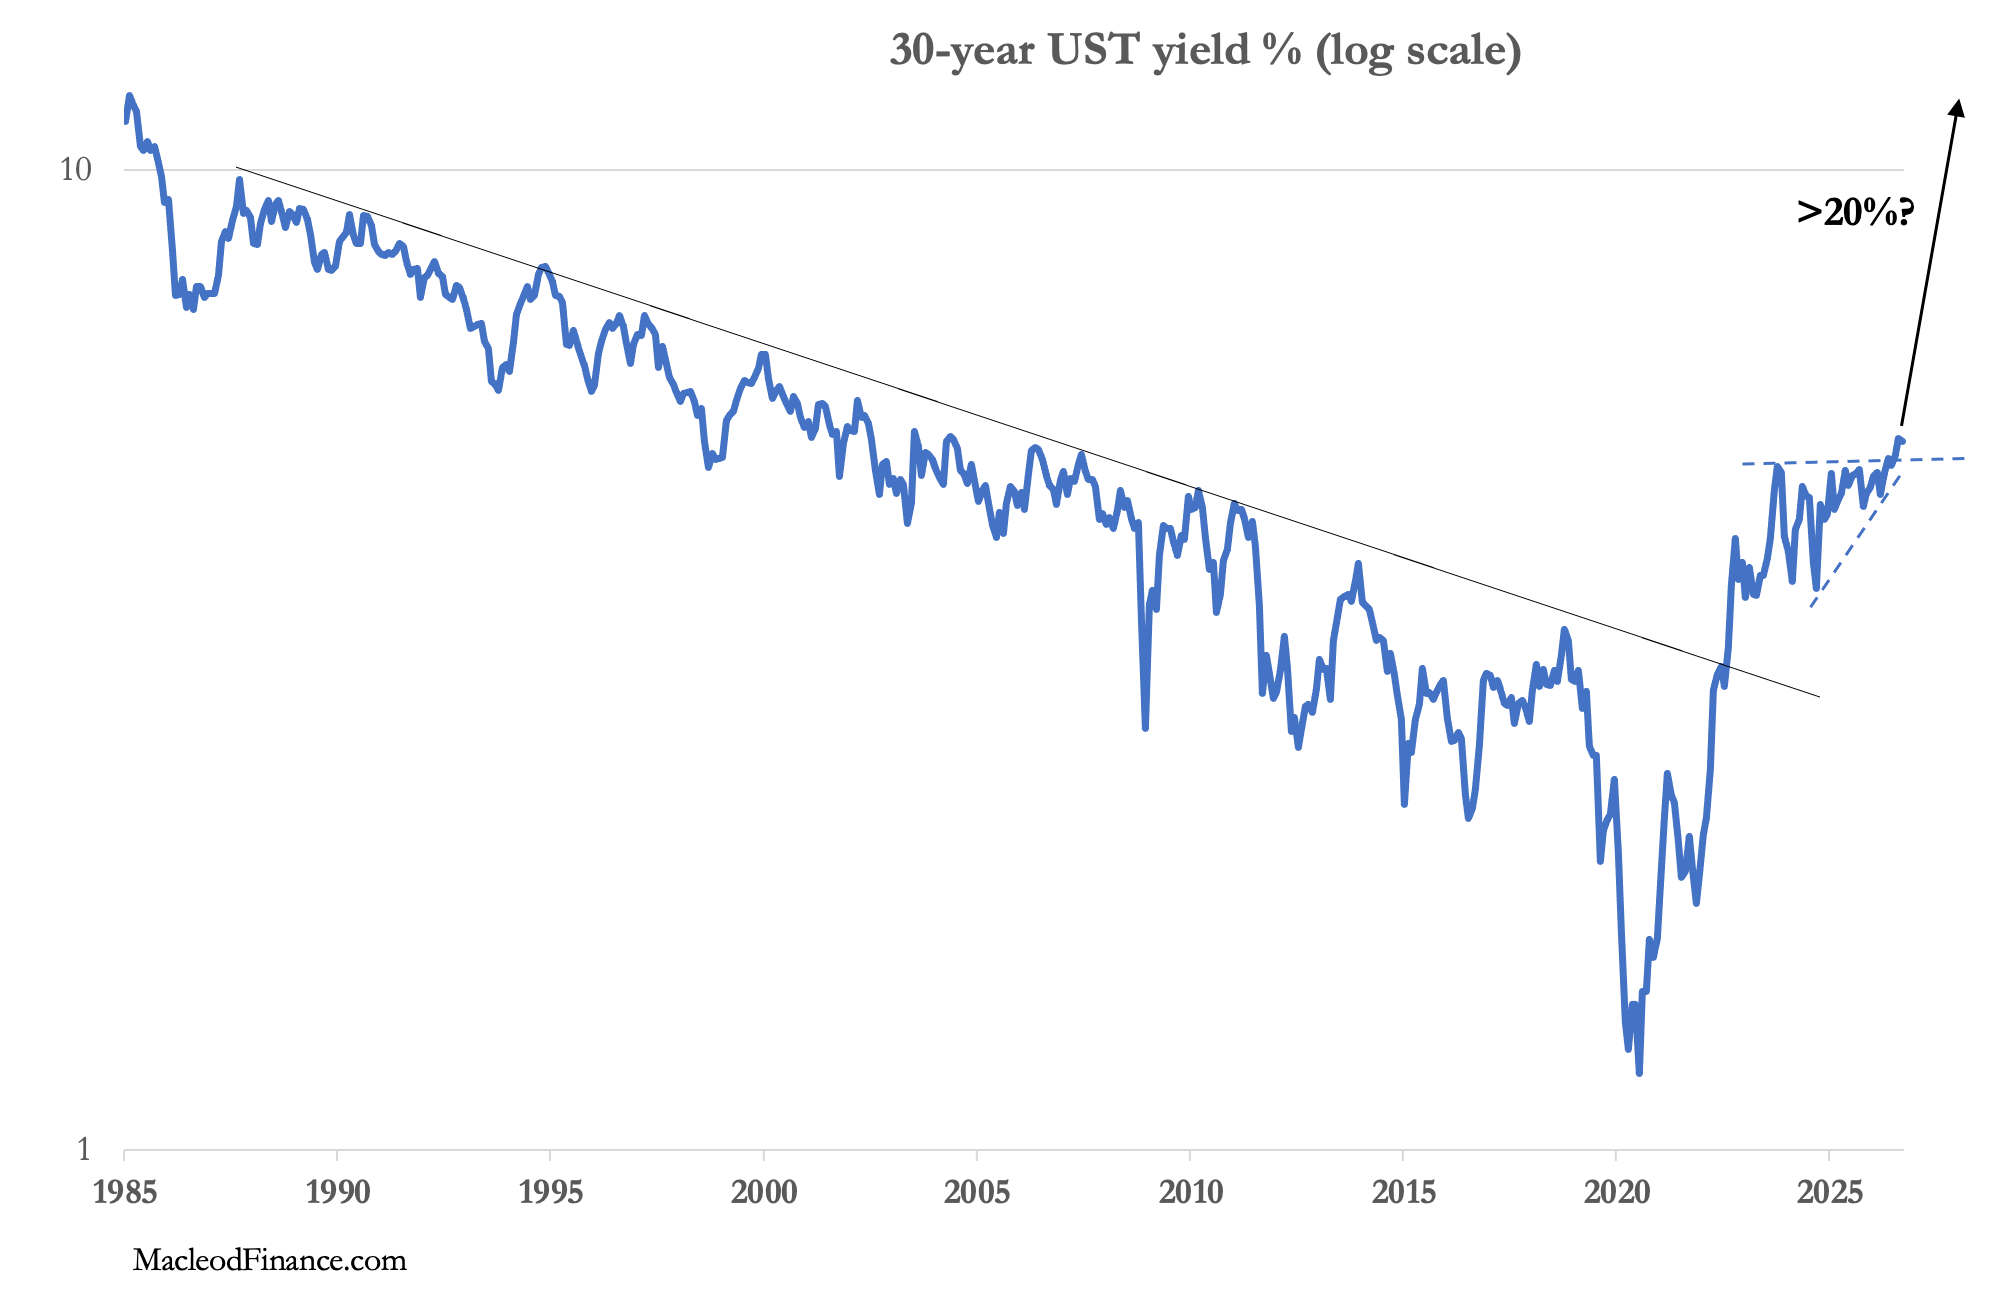
While the yield has yet to exceed the 5% level, it appears to be a hurdle which will be easily overcome because these chart formations, commonly termed pennants after their shape, tend to mark the half-way point in an ongoing trend. This is best illustrated in the chart of the long bond, which is already embarking on the next leg higher. This is next:


Note that this chart is on a logarithmic value scale, illustrating how the percentage move of 250% from the 1.9% low to 5% could run to well over 10% from the breakout over the same brief timescale. The fundamental justification is a combination of the Hormuz and Bab el-Mandab blockades, the debt trap sprung on US government finances, the end of the petrodollar leading to surplus dollar balances in foreign hands, and the global loss of confidence in the dollar from an American geopolitical defeat.

This move to far higher bond yields will almost certainly trigger massive selling of the dollar, a point addressed later in this article. It is a racing certainty that the Secretary Bessent will order the suspension of trading in bonds and equities, as his predecessor William MacAdoo did in July 2014. That time, Wall Street remained shut until the following December. A prolonged market closure today to stop foreign and domestic selling is a real possibility. Don’t get trapped, because if it happens, markets will open considerably lower and investors will face large losses on their investments and on the currency as well.

I shall write about this possibility in a future post.

 
No one can stop what is coming.
All know a market correction is coming and has been for several years.
The everywhere, everything debt is likely close to reaching its peak before the great fall and that is no secret.
Still, it could happen next week or next year or a few years from today.

It is NOT this- :hof:
 
No body wants to buy our debt. America is buying its own debt with borrowed money on the short end like T bills and paying off the long end for notes and bonds with this short term borrowing. We are going down and the speed is going to reach light speed soon.i
In nature...when food is scarce...the snake will attack its own tail out of desperation.
 
LOL.... Yeah, because it's never been over 5% before....

Oh, wait....

View attachment 619100
Context
..
    • The late-2023 spike was driven by strong economic data and comments from Federal Reserve officials indicating interest rates might stay higher for longer to combat inflation.
      faviconV2
      CNBC +2
You can track current rates using the YCharts 10 Year Treasury Rate Tracker.


Confucius say to Glasshoppsa...If tiger no get meat
...he turn into PAPER TIGER.
grok insisted on a poem.


Paper Tiger, Market Roar


The screens all glow with stripes of green and red,
a beast of charts and numbers, fed by fear.
It growls in headlines, shakes the trader’s head,
and makes the timid sell before the year.
Its teeth are tariffs, threats of 100 percent,
its claws are tweets that promise fire and flood.
Yet when the exemptions quietly get sent,
the roar dissolves to ink and printer mud.
A token’s crown: six billion, bright and grand,
until a trickle of sell orders hits.
The throne collapses, scattered through the land—
a paper tiger built on feet of sand.
The strait that might choke oil, the map so stark,
the drones, the drums, the sabers in the night.
But tankers turn, the hedges do their work,
and price forgets the panic by first light.
So learn the lesson written in the tape:
not every shadow means a coming bite.
Some tigers are just headlines, thin as paper,
that rustle, fold, and vanish with the light.


Grok and me.
 
Last edited:
The late-2023 spike was driven by strong economic data and comments from Federal Reserve officials indicating interest rates might stay higher for longer to combat inflation.
I, for one, like the 10 year at a higher rate... It makes CD rates higher and High Yield Savings rates higher... Good for me...

But I don't have any personal credit tied to the 10 year, like credit card balances, mortgages, personal loans, car loans, RV loans, etc.... so it's a non-issue.

Plus, go back up and look at the chart I posted.. The historic average over multiple decades has it over 5%.... and guess what?

You're still here and posting, and survived all those past year... so the apocalypse ain't here...

And since when, do poems, act as financial information?? Strange??
 
LOL.... Yeah, because it's never been over 5% before....

Oh, wait....

View attachment 619100
Preaching the propaganda narrative for Trumpenstein requires that you understand the basics of economy, finance, geopolitics and the their extension- military capabilities.

You clearly are overlooking the fact that our national debt is NOW over $40trillion. It is already decided by our economic condition, as doctor_fungcool points out, that our economy sucks. Further, it is hollowed out with minimal manufacturing, broken supply chains, corrupted trade deals, a decayed military, a profiteering military-industrial complex, and a compromised political system. Now here is the clincher:

Each 0.1% increase in our bond rates adds roughly $70 billion in net interest payments annually for each $7 trillion of debt refinanced in a given fiscal year. This gets complicated with the fact that as interest rates rise, bond prices go down. In a downward spiral- dollar devaluation, no buyers of bonds, economy stagnates further... repeat, repeat... we are no longer able to legally maintain the debt.

The bond market in the US (govt & commercial) is about $60trillion. Our fake currency system is a debt ponzi scheme. All "money" is debt. If all debts were paid off, there would be no "money". It is all backed by "faith" in the system. In a crisis, faith falters. Contracts fail. Debt is dissolved or resolved. The economy crashes by design and the great reset happens.

We are on the road of destruction. The exorbitant political (and military) expenditures exacerbate the bond rates increasing the debt an additional $70 billion for each 0.1%. How long can we put off the reckoning when the bond rates go up 5% as faith is lost in the system? How will people survive on fixed or no income while the US dollar loses 50% of its value each year?
 
Preaching the propaganda narrative for Trumpenstein requires that you understand the basics of economy, finance, geopolitics and the their extension- military capabilities.

You clearly are overlooking the fact that our national debt is NOW over $40trillion. It is already decided by our economic condition, as doctor_fungcool points out, that our economy sucks. Further, it is hollowed out with minimal manufacturing, broken supply chains, corrupted trade deals, a decayed military, a profiteering military-industrial complex, and a compromised political system. Now here is the clincher:

Each 0.1% increase in our bond rates adds roughly $70 billion in net interest payments annually for each $7 trillion of debt refinanced in a given fiscal year. This gets complicated with the fact that as interest rates rise, bond prices go down. In a downward spiral- dollar devaluation, no buyers of bonds, economy stagnates further... repeat, repeat... we are no longer able to legally maintain the debt.

The bond market in the US (govt & commercial) is about $60trillion. Our fake currency system is a debt ponzi scheme. All "money" is debt. If all debts were paid off, there would be no "money". It is all backed by "faith" in the system. In a crisis, faith falters. Contracts fail. Debt is dissolved or resolved. The economy crashes by design and the great reset happens.

We are on the road of destruction. The exorbitant political (and military) expenditures exacerbate the bond rates increasing the debt an additional $70 billion for each 0.1%. How long can we put off the reckoning when the bond rates go up 5% as faith is lost in the system? How will people survive on fixed or no income while the US dollar loses 50% of its value each year?
A commenter finds this funny.
 

Thank you. Really interesting and FACTUAL article that avoids overemotional claptrap. Short plot explanation:

  • S&P 500 corrections are common. Since 1950, the index has experienced around 38 corrections (10%+) and 14 bear markets (20%+).
  • Recovery times vary widely. Typical corrections have recovered in 3-8 months, while major bear markets have often taken 1-2 years or longer.
  • The deepest post-1950 decline occurred during the 2007-2009 Global Financial Crisis, when the S&P 500 fell 56.8% before recovering in 2013.
  • The fastest major recoveries followed the 2020 COVID-19 crash and the 2025 market correction, with the latter reclaiming its previous high in about 89 trading days after a decline exceeding 15%.
  • The type of crisis matters. External shocks have historically rebounded faster than systemic financial crises, which typically require longer recoveries.
  • History provides context, not certainty. Every post-1950 S&P 500 correction has eventually recovered, but future market performance and recovery timelines are never guaranteed.

Equally as short of an explanation:
What goes up will come down. What goes down will go back up based on historical data and facts. Money can be made going in either direction. So be prepared and stop shaking in your boots.

Personal anecdote:
During 2007/2008 when everyone ran around crying and moaning, hubby and I more than doubled our business and set ourselves up for two decades and beyond of financial success. During the 2019/2020 Covid fiasco, we made a tidy sum as well by having already paid off our debt and prepositioned ourselves to take advantage of other people's failures.


Historical anecdotes and facts:
Most of the "new wealth" post the Great Depression came about as a result of people taking advantage of opportunities offered during that financial era. Corrections can be gifts, you just have to keep your eyes open.

Here's a funny one from Florida:
 
Equally as short of an explanation:
What goes up will come down. What goes down will go back up based on historical data and facts. Money can be made going in either direction. So be prepared and stop shaking in your boots.
And there it is^^^^

I really wish people would start thinking more today, instead of emoting... the history and data is out there, but very few try and access it.

It's really easy to go back and look at the history of the 10 year... when it was 7%, 10%, 12%, 15%, and see how it was handled in the economy... Hell, many people here had mortgage rates in the double digits back then, tied to the 10 year, yet everyone survived...
 
Thank you. Really interesting and FACTUAL article that avoids overemotional claptrap. Short plot explanation:

  • S&P 500 corrections are common. Since 1950, the index has experienced around 38 corrections (10%+) and 14 bear markets (20%+).
  • Recovery times vary widely. Typical corrections have recovered in 3-8 months, while major bear markets have often taken 1-2 years or longer.
  • The deepest post-1950 decline occurred during the 2007-2009 Global Financial Crisis, when the S&P 500 fell 56.8% before recovering in 2013.
  • The fastest major recoveries followed the 2020 COVID-19 crash and the 2025 market correction, with the latter reclaiming its previous high in about 89 trading days after a decline exceeding 15%.
  • The type of crisis matters. External shocks have historically rebounded faster than systemic financial crises, which typically require longer recoveries.
  • History provides context, not certainty. Every post-1950 S&P 500 correction has eventually recovered, but future market performance and recovery timelines are never guaranteed.

Equally as short of an explanation:
What goes up will come down. What goes down will go back up based on historical data and facts. Money can be made going in either direction. So be prepared and stop shaking in your boots.

Personal anecdote:
During 2007/2008 when everyone ran around crying and moaning, hubby and I more than doubled our business and set ourselves up for two decades and beyond of financial success. During the 2019/2020 Covid fiasco, we made a tidy sum as well by having already paid off our debt and prepositioned ourselves to take advantage of other people's failures.


Historical anecdotes and facts:
Most of the "new wealth" post the Great Depression came about as a result of people taking advantage of opportunities offered during that financial era. Corrections can be gifts, you just have to keep your eyes open.

Here's a funny one from Florida:
FWIW, Quincy wasn't the only north Florida small town where investing in Coca Cola was a big thing during the Depression. 70 miles to the east Madison, FL had families who were Coca Cola millionaires thanks to the same advice to invest in the company.
 
Thank you. Really interesting and FACTUAL article that avoids overemotional claptrap. Short plot explanation:

  • S&P 500 corrections are common. Since 1950, the index has experienced around 38 corrections (10%+) and 14 bear markets (20%+).
  • Recovery times vary widely. Typical corrections have recovered in 3-8 months, while major bear markets have often taken 1-2 years or longer.
  • The deepest post-1950 decline occurred during the 2007-2009 Global Financial Crisis, when the S&P 500 fell 56.8% before recovering in 2013.
  • The fastest major recoveries followed the 2020 COVID-19 crash and the 2025 market correction, with the latter reclaiming its previous high in about 89 trading days after a decline exceeding 15%.
  • The type of crisis matters. External shocks have historically rebounded faster than systemic financial crises, which typically require longer recoveries.
  • History provides context, not certainty. Every post-1950 S&P 500 correction has eventually recovered, but future market performance and recovery timelines are never guaranteed.

Equally as short of an explanation:
What goes up will come down. What goes down will go back up based on historical data and facts. Money can be made going in either direction. So be prepared and stop shaking in your boots.

Personal anecdote:
During 2007/2008 when everyone ran around crying and moaning, hubby and I more than doubled our business and set ourselves up for two decades and beyond of financial success. During the 2019/2020 Covid fiasco, we made a tidy sum as well by having already paid off our debt and prepositioned ourselves to take advantage of other people's failures.


Historical anecdotes and facts:
Most of the "new wealth" post the Great Depression came about as a result of people taking advantage of opportunities offered during that financial era. Corrections can be gifts, you just have to keep your eyes open.

Here's a funny one from Florida:
Clap trap wisdom from.DA MAN WB.


Warren Buffett is not predicting a market CRASH yet, but he is exercising extreme caution and sitting on record amounts of cash because he views current stock prices as too high.
 
Yes yes yes, but the interest on our debt can’t go up now. This won’t end well. This isn’t the same as before, IMHO. I may be wrong, but this doesn’t feel the same.

It does not feel the same because it is not the same.

Servicing the current US debt at say for example 5% today is not remotely the same as servicing the US debt at 5% 20 year ago because the debt servicing costs have exploded in the last few years. This is why you cannot look at just an interest rate chart in isolation and compare rates today vs 10, 20, or 30 years ago - 5% today has a very different effect than 5% in the past. The US debt situation has radically changed, so the impact of rising interest rates will likely be quite different this time around.

Fiscal Data Explores Interest Expense on National Debt
 
Yes yes yes, but the interest on our debt can’t go up now. This won’t end well. This isn’t the same as before, IMHO. I may be wrong, but this doesn’t feel the same.

Every time things happen they are different in some respects. There a number of people who think they are allowing the debt to pack on now so that when they revalue and change to a purely digital currency it will give the US a considerable amount of leverage.

A change in currency is pretty much baked in. Study the history of when various countries left the gold. The US wasn't first by a long shot. We have a perfect storm, we just don't know when it is going to break or what is going to do the breaking.

And then there is the political pressures that groups like the DSA is creating. They have at least as much reason to convert to digital currency as any other entity you can name here in the US.

People need to prepare however they can prepare, just with serious care in case it takes longer to occur than the immediate doomers think. I suspect we still have several binge/purge financial cycles to get through and you need to position yourself to take advantage of them. Not just survive, but take advantage of them. That is going to require a mindset based on facts, not emotions.
 
Top